What is market risk in a trading book?
Select an option, then click Submit answer.
- ○ Loss from adverse price movements
- ○ Loss from borrower loan defaults
- ○ Loss from internal process failures
- ○ Loss from natural disaster damage
Loading demo links...
Showing 1–12 of 12 questions
What is market risk in a trading book?
Select an option, then click Submit answer.
What does a delta measure for an options position?
Select an option, then click Submit answer.
What does gamma add to delta hedging understanding?
Select an option, then click Submit answer.
Why do trading desks operate under VaR limits?
Select an option, then click Submit answer.
What is the holding period assumption in VaR?
Select an option, then click Submit answer.
What does incremental VaR show about a new trade?
Select an option, then click Submit answer.
Which two are market risk measurement methods? (Choose two.)
Select all that apply, then click Submit answer.
Which two are components of market risk governance? (Choose two.)
Select all that apply, then click Submit answer.
Which two shocks are used in trading stress tests? (Choose two.)
Select all that apply, then click Submit answer.
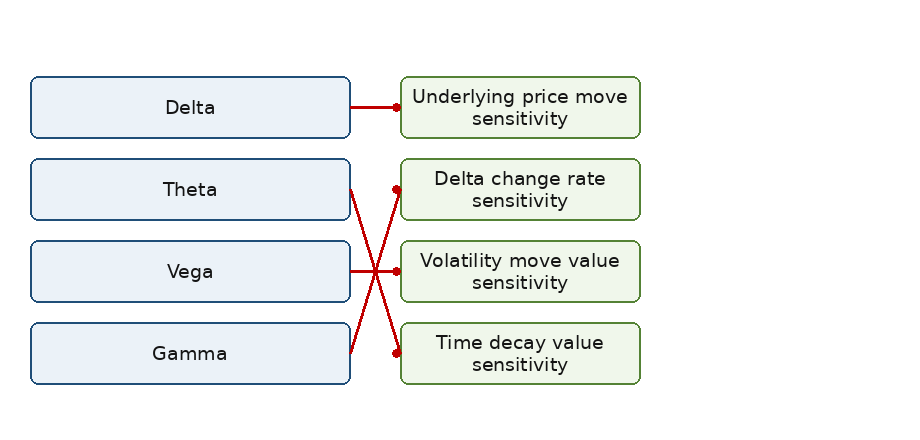
DRAG DROP
Match each Greek to its sensitivity.
Items to match: Delta, Gamma, Vega, Theta.

Answer is in the explanation below.
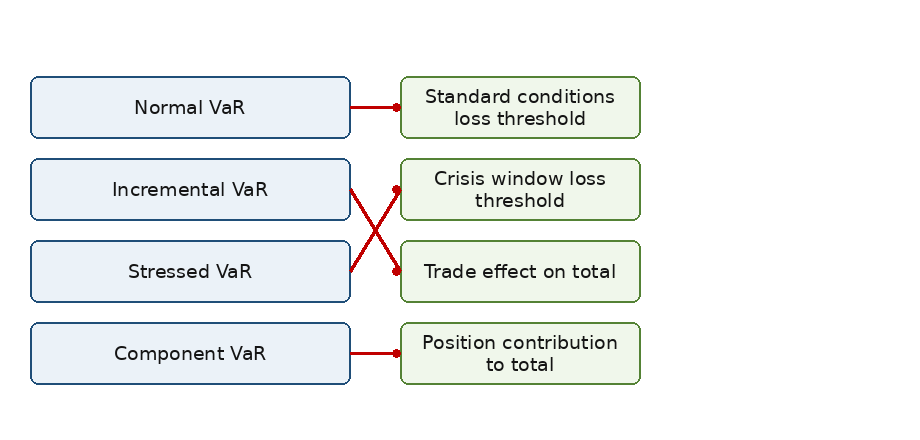
DRAG DROP
Match each VaR variant to its purpose.
Items to match: Normal VaR, Stressed VaR, Incremental VaR, Component VaR.

Answer is in the explanation below.
CORRECT TEXT
The options sensitivity to implied volatility is called ______.
Answer is in the explanation below.